Systems · September 27, 2026
The Moat Is Rented
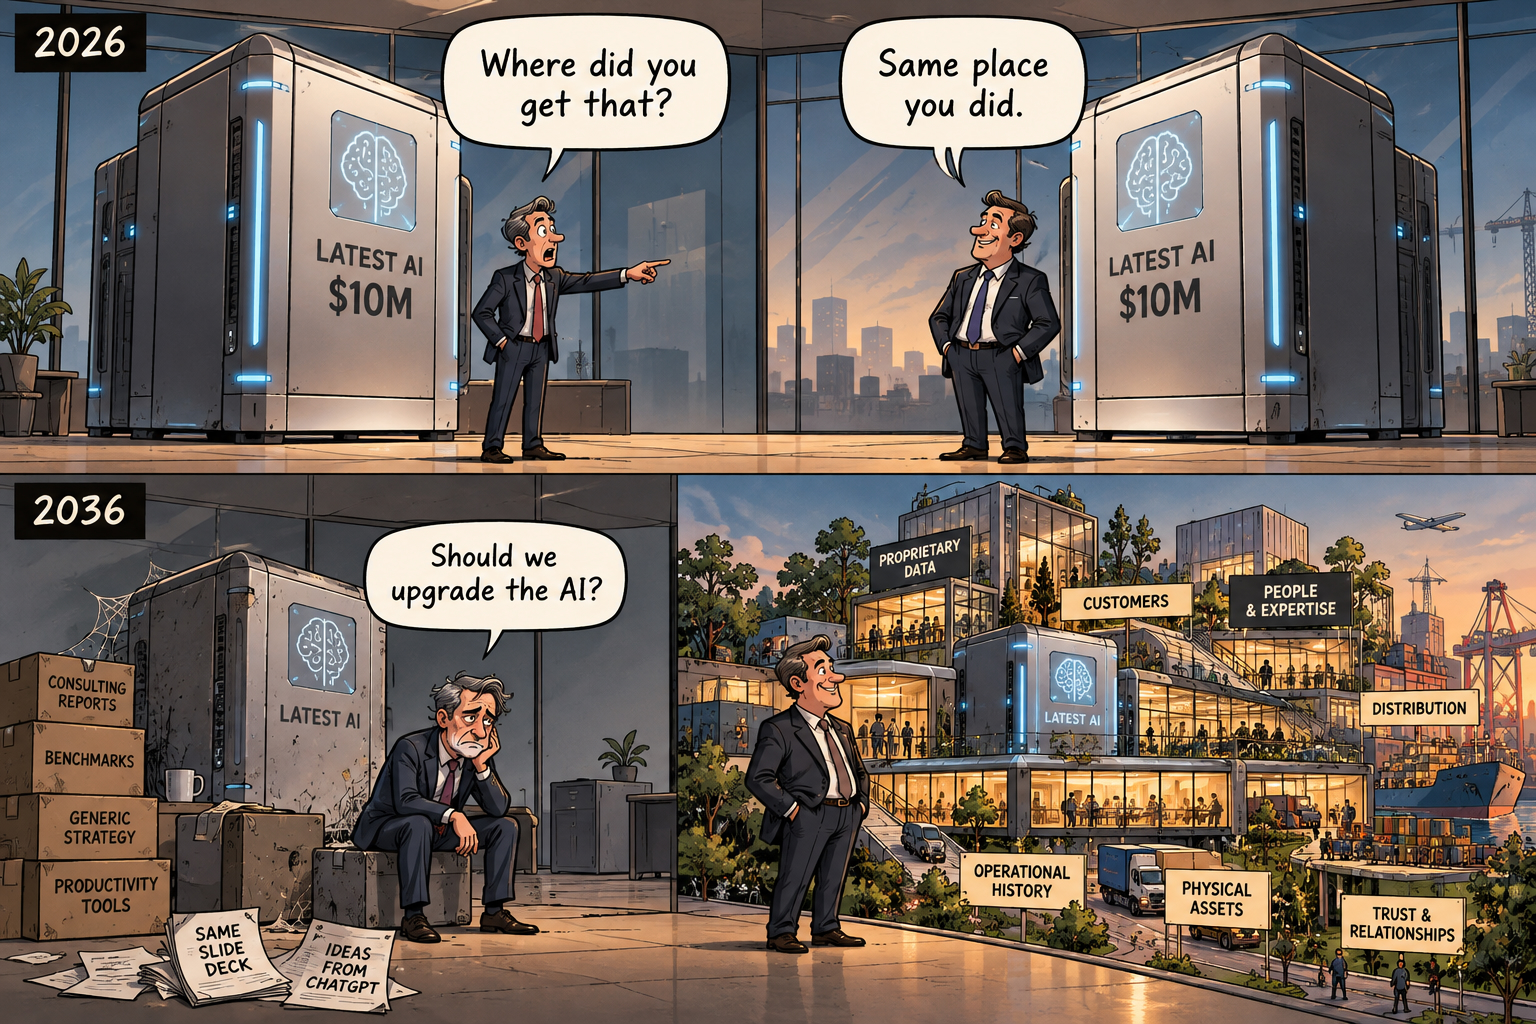
Eight in ten say AI has made them more productive. Fewer than four in ten say it has contributed to their organization's earnings.
AI is making a lot of good work much cheaper. Research that once took days can take hours. A competent first draft appears in seconds. Code, analysis, presentations, process maps, customer research, strategy documents and architecture diagrams can all be produced faster, and increasingly well. This is overwhelmingly useful, and it creates a strategic problem. If everybody can buy roughly the same capability, being good at that capability stops being much of an advantage.
McKinsey made the point directly in May in its work on AI and competitive moats. Nearly nine in ten organizations now use AI in at least one business function, and most of them are deploying the same large language models to chase the same productivity gains. The conclusion is obvious once stated: if everyone has the same advantage, nobody has one. [1]
We've seen this before. A website was once an advantage, then everybody had one. Mobile apps followed, then cloud infrastructure. McKinsey's own banking analysis found that mobile-app adoption rose between 2018 and 2022 without leaders widening their lead over laggards. The gap widened where digital and AI ran through the whole customer journey rather than sitting in an app. [1] Nicholas Carr made the general case in Harvard Business Review in 2003: technologies like the railways and electric power open a short window of advantage while they're being built out, and once they're cheap and everywhere they become commodity inputs, essential to the business and invisible to strategy. [2] The technology stays valuable, often enormously so. Access to it stops separating one company from another. AI is doing this at a larger scale because the thing becoming cheap is intelligence work itself.
The pull toward the middle
There's a second effect, and it's starting to show. AI can improve an individual's work while making the work of a group more alike.
Doshi and Hauser tested this in an experiment published in Science Advances in 2024. People writing short stories who were given access to GPT-4 story ideas produced work judged more creative, better written and more enjoyable, with the largest gains among the less creative writers. The AI-assisted stories were also more similar to each other. The authors describe the result as resembling a social dilemma: each writer individually better off, the group collectively narrower. [3]
A 2025 study by Moon, Green and Kushlev at Georgetown compared 2,200 college admissions essays across three preregistered studies. Each additional human-written essay added new ideas at roughly two to eight times the rate of each additional GPT-4 essay. When the researchers changed the model's settings to make its writing more varied, the individual GPT-4 essays became more semantically diverse than the human ones, and the set of them still converged faster. Chain-of-thought prompting narrowed the gap, and the human essays still grew the pool of ideas about twice as fast. [4] Each essay on its own looked more creative. Together, they looked the same.
These are writing studies, not experiments in corporate strategy, and they don't prove that businesses using AI will make the same decisions. They do show a mechanism. Large models are trained on the accumulated record of what people have already written. Ask one for established approaches, industry patterns, benchmarks, risks, operating models or strategic options and it's exceptionally good at finding the center of what is already known. Give broadly similar tools to every company in an industry and the gravitational pull isn't hard to see.
There's already a recognizable AI texture in business: the same language, the same diagrams, the same four-box frameworks, the same exhaustive lists of risks and opportunities. Strategy documents are becoming easier to produce at precisely the moment producing one has become less impressive. A mountain of competent work is still a mountain.
What happens to the savings
None of this is an argument against using AI to cut costs. If something that costs $1 million can be done properly for $300,000, take the $700,000. The problem starts when the saving is described as strategic differentiation.
Tanguy Catlin, a McKinsey senior partner and a director of the McKinsey Global Institute, put the economics plainly on the firm's podcast in July. Competitors have access to the same technology and pursue the same productivity gains, so little of the value sticks to any one company. Most of the surplus gets passed to customers, or to the service providers paid to implement the technology. [5] A consultant telling you the money ends up with customers and consultants is at least candid. Competitors adopt the same capability, prices adjust, customers expect more, and yesterday's advantage becomes tomorrow's admission price.
McKinsey's latest State of AI survey, published in August from 1,719 respondents, shows the pattern in the numbers. Eight in ten say AI has improved their own productivity. Thirty-seven percent say it has contributed to their organization's EBIT, a share essentially unchanged from a year earlier, even though the proportion scaling AI across the enterprise has risen to 44 percent. [6] Adoption is close to universal. The individual gains are real. The P&L mostly can't see them. McKinsey's own explanation is that the few who capture value rebuild workflows rather than bolt AI onto existing ones. Catlin's economics supply a second: when everyone makes the same improvement at the same time, there's little left for any one company to keep.
That's the general case, and it has an exception. AI becomes part of a moat when it's plugged into something that compounds: data that improves with every interaction, a workflow rebuilt around the model rather than decorated with it, a physical asset the model makes more productive. The model itself is rented. What accumulates is whatever it's wired into.
Which changes the questions I'd want a board to ask. Instead of how much productivity an AI investment creates, ask what becomes harder for a competitor to reproduce because we made it. And if our competitors achieve roughly the same productivity improvement, what advantage remains? Sometimes the honest answer is nothing. That's fine. It may still be a good investment, because lower costs matter. It isn't a moat.
Strategy theory has been saying a version of this for decades. Jay Barney's resource-based view argued that sustained advantage comes from resources that are valuable, rare, hard to imitate and hard to substitute. Dierickx and Cool went further: some advantages have to be accumulated over time because they can't be bought in any market. History matters. Learning matters. The order in which capabilities were built matters. [7] AI doesn't make that thinking obsolete. It makes it more relevant, because it's removing "rare" from a growing list of capabilities.
The things AI can't download
I recently listened to Caleb Ralston, a brand strategist who has worked with Alex Hormozi and Gary Vaynerchuk, talking about personal brands. His argument was that people copy what already works, down to the fake plant, the bookshelf and the colored lights behind the camera, and end up as a slightly modified version of the most successful person in their niche. His advice was to start somewhere else: with what you've actually done, what you've learned and where your view differs from the accepted one.
Companies have their own fake plant and bookshelf. They benchmark the same competitors, commission the same research, hire from the same talent pools, implement the same platforms and now feed similar questions into similar models. The interesting assets sit elsewhere. Thirty years of customer behavior. Failed products and the reasons they failed. Operational data nobody outside the business possesses. Trust earned slowly in a difficult market. Distribution relationships. Informal knowledge held by people who've been solving the same ugly problem for twenty years. A regulatory capability built through experience rather than a compliance slide. The odd engineering decision that looks inefficient until you understand the environment it survived. For industrial, logistics, energy and infrastructure businesses, add the assets that are scarce in the physical world: an installed base, a port, a network, a license. Those are harder to reproduce than another dataset, because reproducing them takes capital, years and often regulatory approval, and AI applied to them makes them more productive without making them available to anyone else. [1]
Rohan Narayana Murty and Ravi Kumar S made a related argument in Harvard Business Review in February. When companies can access the same models, tools and vendors, organizational context becomes the differentiator, and their definition of context is practical: how work actually moves between systems, which signals people act on, which exceptions trigger a response, and the judgment calls experienced people make that never reached the documented process. [8] Murty runs a company that sells organizational context to enterprises deploying AI agents. Kumar is the CEO of Cognizant. McKinsey, for its part, sells rewiring. Every commercial source in this article concludes that the durable advantage is the part it invoices for. The argument survives the conflict, but it should be weighed with the conflict in view.
That context is valuable because it was accumulated rather than purchased. AI can make it more useful: find patterns in it, make inaccessible information searchable, connect fragments of institutional knowledge and feed new information back into the system. That's a different proposition from buying an assistant for everyone and counting the hours saved.
Who owns the learning
If the moat is proprietary data and accumulated context, and both are being pushed through a vendor's model, a board question follows directly: who owns what the system learns, and what leaves with the vendor? McKinsey's moats paper says it without hedging. Every workflow handed to an embedded AI system is a wager on that vendor's future direction, pricing and survival, and data rights and portability belong in the negotiation up front, with the learning retained in a form you can use. [1] Enterprise agreements from the major vendors generally exclude training on customer data, so the risk is rarely theft. The open question is exit. If the accumulated judgment of your operation now lives inside someone else's system, check the terms, and check that you could leave with it.
Ten years is a more useful horizon
Most businesses can't ignore the short term. Listed companies have reporting cycles, private companies have cash flow, and boards have budgets, covenants, investors and people who would reasonably prefer to be paid this month rather than in 2036. Short-term decisions are part of running a company. They become dangerous when the organization gets so good at optimizing the next period that nobody is building what will matter several periods from now.
There's an old exercise of imagining your own funeral and working backwards from what mattered. Morbid, and useful. Companies could do with a version involving fewer coffins. Imagine the business ten years from now and assume it's still unusually successful. What would have to be true? It probably won't be that the company adopted Microsoft Copilot six months before its competitors, or that its developers generated code faster for three quarters. Those things may contribute, but competitors can catch them. Something will have accumulated. Customer knowledge. Proprietary data. Distribution. Reputation. Network effects. Physical infrastructure. Deep expertise. Better feedback loops. A way of operating that took years to learn. Usually several of them, reinforcing each other.
McKinsey's moats work describes the same pattern. Privileged data becomes more valuable when every interaction improves it. AI embedded in core workflows becomes harder to remove as the systems learn and people adapt around them. Physical assets combined with AI become more productive without becoming available to everyone else. [1] Those are compounding assets. Saving 30 percent on producing a report is useful this year. Building something that gets harder to reproduce every year is a different kind of return, and that distinction belongs much closer to the center of AI strategy than it currently sits.
The exercise is short. Pick the three things that would need to be substantially stronger in ten years for the company to still have an advantage. Then ask whether a well-funded competitor could simply buy them.
The technology is becoming astonishingly capable and access to it is spreading fast. Use it, and don't confuse possession of the tool with possession of an advantage. Competence is getting cheap. What was accumulated slowly is getting more valuable, and it's usually the part that doesn't come in the box.
Sources
1. Dago Diedrich, Evan Williams, Tanguy Catlin and Tim Fountaine, "From AI table stakes to AI advantage: Building competitive moats," McKinsey Quarterly, May 15, 2026. https://www.mckinsey.com/capabilities/quantumblack/our-insights/from-ai-table-stakes-to-ai-advantage-building-competitive-moats
2. Nicholas G. Carr, "IT Doesn't Matter," Harvard Business Review, May 2003. https://hbr.org/2003/05/it-doesnt-matter
3. Anil R. Doshi and Oliver P. Hauser, "Generative AI enhances individual creativity but reduces the collective diversity of novel content," Science Advances 10(28), July 12, 2024. https://doi.org/10.1126/sciadv.adn5290
4. Kibum Moon, Adam E. Green and Kostadin Kushlev, "Homogenizing effect of large language models (LLMs) on creative diversity: An empirical comparison of human and ChatGPT writing," Computers in Human Behavior: Artificial Humans 6 (2025), 100207. https://doi.org/10.1016/j.chbah.2025.100207
5. Tanguy Catlin, "The real AI advantage," The McKinsey Podcast, July 9, 2026. https://www.mckinsey.com/mgi/our-research/the-real-ai-advantage
6. McKinsey, "The state of AI in 2026: On the road to ROI," August 25, 2026. https://www.mckinsey.com/capabilities/quantumblack/our-insights/the-state-of-ai
7. Jay B. Barney, "Firm Resources and Sustained Competitive Advantage," Journal of Management 17(1), 1991, pp. 99-120. https://doi.org/10.1177/014920639101700108. Ingemar Dierickx and Karel Cool, "Asset Stock Accumulation and Sustainability of Competitive Advantage," Management Science 35(12), 1989, pp. 1504-1511. https://doi.org/10.1287/mnsc.35.12.1504
8. Rohan Narayana Murty and Ravi Kumar S, "When Every Company Can Use the Same AI Models, Context Becomes a Competitive Advantage," Harvard Business Review, February 18, 2026. https://hbr.org/2026/02/when-every-company-can-use-the-same-ai-models-context-becomes-a-competitive-advantag